

Quicken: Intelligent Money

- 1.36K Reviews
- 4.7
- Downloads
- 500,000+
Our take on Quicken: Intelligent Money from Appgk
I spent time with Quicken: Intelligent Money as a personal finance app, and my first impression was that it is aimed at people who want more than a quick glance at their bank balance. It is built around budgets, spending awareness, and broader financial organization, with tools that also reach into small-business money management. That wider scope makes it more interesting than a simple expense notebook, but it also means you get the best results only if you are willing to keep your financial information organized.
The app is developed by Quicken Inc. and is available for free, with optional in-app purchases ranging from $9.99 to $109.99 per item. That detail matters because the free entry point does not automatically mean every useful part of the experience is free. I would look at it as a way to explore the workflow before deciding whether the paid value fits my finances. The app is rated for Everyone, so its subject matter is suitable for a broad audience, including people beginning to take budgeting seriously.
How Quicken fits into everyday money management
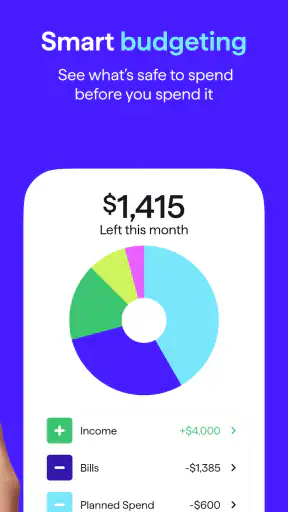
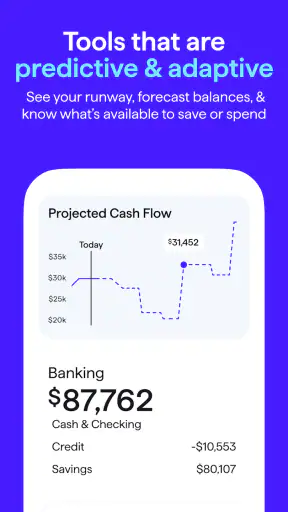
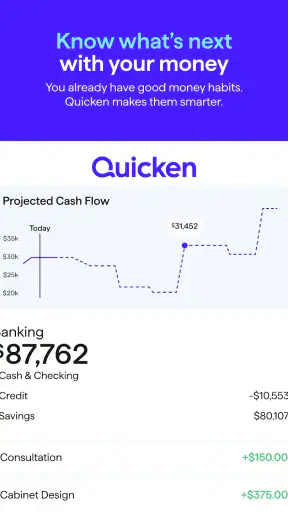
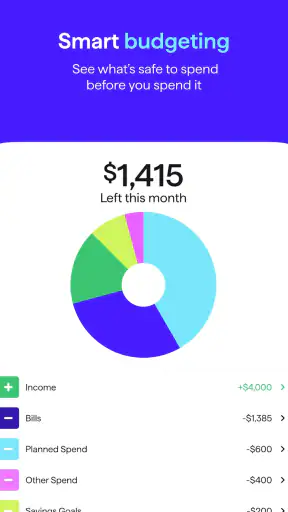
At its core, this is a finance app for turning scattered money decisions into a routine. Instead of asking myself only whether I can afford something today, I can use a budget to think about where my money is going over time. That shift is important. A spending tracker records what happened; a budgeting tool can help me decide what should happen next.
I found the concept most useful when I treated it as a weekly checkpoint rather than an app I would open only after making a large purchase. A short review of recent spending can reveal small habits that are easy to miss in a bank app. A takeaway meal, several small subscriptions, or frequent convenience purchases may not feel significant individually, but their place in a monthly plan becomes clearer when grouped into a budget.
Best Parts of Quicken: Intelligent Money
Things to Keep in Mind About Quicken: Intelligent Money
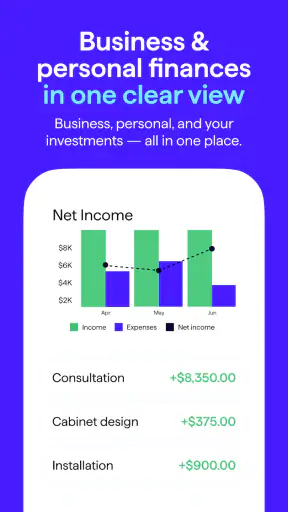
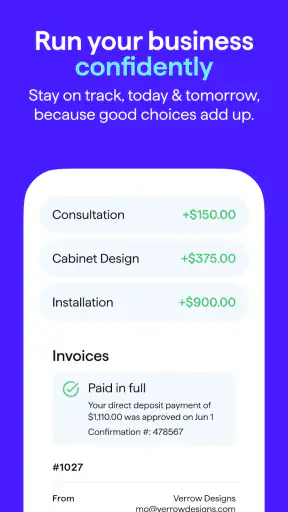
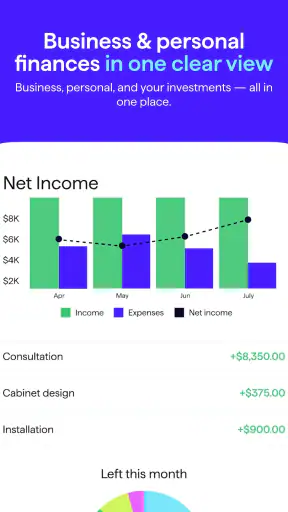
The small-business angle adds another layer. Someone who earns money independently may need to think about personal spending and business-related activity without treating them as one indistinguishable pile. That does not make the app a replacement for professional accounting advice, but it can make day-to-day organization more practical for a freelancer or very small operation that wants a clearer view of cash movement.
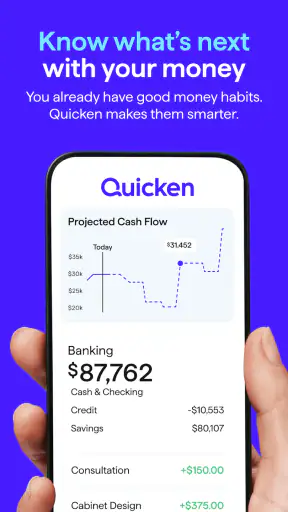
One useful distinction is between monitoring money and making decisions about it. Many banking apps are excellent for showing transactions, balances, and recent activity. Quicken’s appeal is the attempt to place those details inside a planning habit. If I only want to check whether a payment cleared, my bank’s own app may be faster. If I want to compare actual spending with a personal plan, a dedicated finance tool has a stronger reason to exist.
News and Features Related to Quicken: Intelligent Money

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What the free starting point really means
The app costs nothing to download, which lowers the risk of trying it. I can test whether its budgeting approach suits me before committing money. That is especially helpful because personal finance systems are highly individual: one person may enjoy assigning every expense, while another may find that level of attention exhausting.
The important trade-off is that free access and full value are not necessarily the same thing. Optional purchases are listed from $9.99 to $109.99 per item, so I would not assume that the most complete experience comes without a payment. I would first decide what problem I am trying to solve, then check whether the relevant tools are included in the access level I intend to use. This avoids paying for a broader system when a simpler free routine would be enough.
Don't want to read the full review?
I also like that the pricing range encourages a more careful decision than an automatic subscription habit. A lower-cost purchase may make sense for someone who needs a focused budgeting workflow, while a higher-cost option deserves a stronger reason, such as genuinely using the app across personal and small-business finances. The right value depends on how consistently I use the system, not on how many financial features sound attractive at first.
Because finances are personal, I would spend some time testing the basic experience before entering a long-term commitment. I would create a realistic budget, review a normal week of spending, and see whether the process feels clear or burdensome. If I stop checking it after a few days, even a modest purchase is poor value. If it becomes part of my regular money routine, the paid options may be easier to justify.
Screenshots
Where the app can deliver practical value
The strongest benefit is perspective. A balance tells me what is available now, but a budget helps me ask whether that money already has a job. This is useful before rent, utilities, debt payments, groceries, or annual expenses arrive. The app becomes more valuable when I use it to anticipate pressure rather than merely document it afterward.
For example, imagine I receive my salary near the start of the month. I could open the app during the first weekend, set expectations for essential spending, and leave room for irregular costs. Midway through the month, I could compare my actual choices with that plan. If dining expenses are already higher than expected, I have time to adjust instead of discovering the problem after the account is nearly empty.
A less obvious benefit is the ability to make budget conversations more concrete. Couples or families often disagree about whether they are “spending too much” because each person remembers different purchases. A shared review of categories can move the conversation away from blame and toward priorities. I would still agree on the categories and goals outside the app, but the structure can make those discussions less vague.
The small-business tools may be useful in a similar way for a self-employed person who wants to separate business thinking from household decisions. A freelancer can look at incoming work, recurring costs, and personal obligations as different parts of the same financial picture. The key is discipline: I would define a consistent method for classifying money and keep records clear enough that a later review remains understandable.
Another practical insight is to use the app for irregular expenses, not just monthly bills. Annual renewals, seasonal purchases, repairs, and professional costs can destabilize a budget when they appear unexpectedly. I would create room for these expenses in advance rather than treating every unusual payment as a surprise. That approach turns budgeting into preparation instead of restriction.
Trade-offs that matter before committing
The broader the financial system, the more attention it usually demands. I would not recommend this app to someone who wants a completely passive experience. A budgeting tool is only as accurate as the information and decisions behind it. If I ignore transactions, use inconsistent categories, or never revisit the plan, the app cannot turn that neglected information into useful guidance.
There is also a psychological trade-off. Seeing spending organized by category can be motivating, but it can also feel uncomfortable when the numbers challenge familiar habits. I think that discomfort is useful when it leads to a realistic adjustment, not when it encourages an overly strict budget that fails after one difficult week. I would set targets I can actually maintain and revise them when circumstances change.
Compared with a spreadsheet, Quicken offers a more purpose-built environment for people who do not want to design their own formulas, categories, and review process. A spreadsheet can be cheaper and extremely flexible, but it requires more setup and maintenance. I would choose the spreadsheet route if I enjoy building systems or need unusual calculations. I would choose this app if I want a ready-made finance workflow and prefer spending my time interpreting the information.
Compared with a basic notes app or manual expense list, this product is more structured. Notes are fine for a short savings challenge or a handful of recurring bills, but they become awkward when I want to compare plans with actual spending. The trade-off is that a structured finance app asks me to learn its way of organizing money instead of letting me improvise everything.
Compared with a bank’s mobile app, the distinction is even clearer. A bank app is usually the natural place for transactions and account actions, while a dedicated budgeting product is more useful for planning across financial priorities. I would not replace my bank app with Quicken; I would use each for a different job. The bank app answers “what happened in this account?” and the budgeting workflow helps answer “what should I do next?”
Privacy and security are also reasons to think before adding financial information to any third-party tool, even when the app appears convenient. I would read the current permissions, connection details, and privacy terms shown during setup, and I would avoid entering information I do not need for my chosen workflow. That is not a criticism unique to this app; it is simply sensible behavior for any personal finance service.
Small workflows that make it more useful
My preferred approach would be to begin with a short list of meaningful categories rather than trying to represent every possible purchase. Essential housing costs, food, transport, debt, savings, and flexible spending are often enough to reveal the main pattern. Too many categories create administrative work and can make a budget look precise without making it more useful.
I would also separate “planned” from “ideal.” A budget should describe what I can realistically do, not the version of myself who never has an unplanned expense. If I set targets that leave no room for ordinary life, I will constantly feel behind. A more forgiving plan gives me a better chance of maintaining the habit and learning from the results.
For irregular income, I would build the workflow around conservative expectations rather than assuming every month will be strong. A freelancer could use a lower expected income as the baseline and treat stronger months as an opportunity to cover future costs or strengthen savings. The small-business focus makes this kind of thinking particularly relevant, although the app itself cannot decide which tax or accounting treatment is appropriate for an individual situation.
One advanced habit is to review categories after several weeks instead of changing them after every single purchase. Immediate reactions can produce a messy system. A periodic review helps identify whether a category is genuinely too broad, whether a spending target is unrealistic, or whether a one-time expense should be treated differently from a recurring pattern.
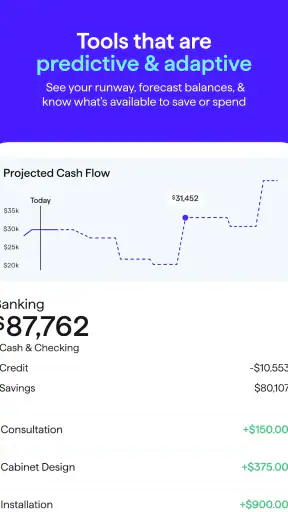
I would also use the app before making a major recurring commitment. A new service, loan payment, or business expense is not just another purchase; it changes future flexibility. Adding it to the budget first can show whether the commitment still works after essentials and existing obligations are accounted for. This is one of the clearest ways a planning tool can protect me from judging affordability by today’s balance alone.
Who will get the most from it
I think the best fit is someone who wants a central place for budgeting and financial review, especially if personal money management is becoming more complicated. It can suit a household preparing for larger goals, a person trying to understand spending patterns, or a freelancer who wants a more deliberate way to look at business and personal finances together.
It may also help someone who has tried a spreadsheet but stopped maintaining it. The value is not that a dedicated app magically makes budgeting easy; it is that a consistent environment can remove some of the friction that causes a homemade system to be abandoned. The test is whether I am willing to return to it regularly and make decisions from what I see.
I would skip it if I only need a very lightweight expense log, a quick balance check, or a basic reminder for bills. In those cases, a bank app, notes app, or simple spreadsheet may be more efficient. I would also hesitate if I dislike categorizing expenses or do not want to spend time reviewing financial information. A more sophisticated tool can become unnecessary overhead when the underlying need is simple.
People with complex accounting, payroll, tax, or compliance responsibilities should be cautious about treating a consumer finance app as their entire professional system. The small-business orientation can be useful for organization, but a growing company may need specialized accounting software and qualified advice. I would use Quicken as a practical management aid only when its scope matches the scale of the work.
My verdict on value
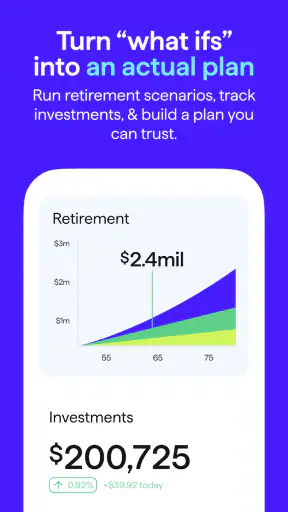
Quicken: Intelligent Money is most convincing when I view it as a planning habit rather than a transaction viewer. Its free price makes experimentation straightforward, while the optional purchases mean I should evaluate paid value based on actual use instead of assuming every user needs the broadest option. The listed age rating of Everyone also makes it approachable for a wide range of people, though financial maturity and willingness to maintain a budget matter more than age alone.
The app has a strong case for users who want to connect everyday spending with longer-term decisions and who may benefit from small-business organization as well. Its main weakness is the same feature that gives it appeal: a wider financial scope can require more attention than a simple tracker. I would not install it expecting instant clarity without doing any review work.
Quicken Inc. has built a recognizable finance product with a 4.7 average from around 4.9 thousand ratings and more than 500 thousand installs, which suggests that many people find the approach worthwhile. Those figures do not decide whether it fits my situation, but they do make it a reasonable candidate to test rather than an obscure experiment.
My recommendation is to start free, create a realistic budget, and use it through an ordinary spending cycle before considering an in-app purchase. If the review process helps me catch patterns, prepare for irregular costs, or separate personal and small-business thinking, paid access may offer meaningful value. If I only want a fast account snapshot or a tiny manual list, I would skip it and choose the simpler tool. Use it when you want a repeatable financial decision system; skip it when tracking alone is all you need.
Quicken: Intelligent Money FAQ
What is Quicken: Intelligent Money, and what can I use it for?
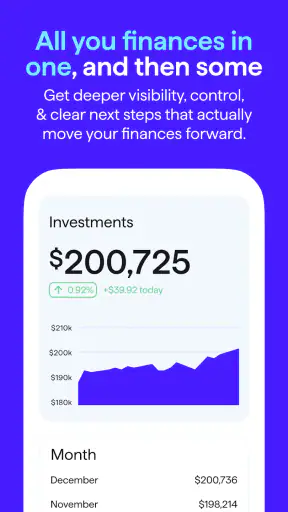
Quicken: Intelligent Money is a personal finance app designed to help you organize and monitor your financial life in one place. It can be used to track spending, review account balances, manage budgets, follow bills, and understand changes in your overall financial position. The app is most useful for people who want a clearer picture of their everyday money without relying on scattered bank statements or spreadsheets.
Can Quicken: Intelligent Money connect to my bank and other financial accounts?
The app is designed to connect with supported financial institutions so that transactions and balances can be brought into your financial dashboard. Availability can vary depending on your bank, country, account type, and the connection method being used. Before downloading or subscribing, check whether your institutions are supported. You should also review the permissions and security information carefully before linking any sensitive accounts.
Is Quicken: Intelligent Money free to download and use?
Quicken: Intelligent Money may be available to download without an upfront charge, but some features can require a subscription or an in-app purchase. The exact price, trial period, plan limits, and included tools may change over time and can differ between Android and iOS. It is worth checking the store listing and subscription screen before starting a trial, especially because subscriptions may renew automatically.
How secure is my financial information in Quicken: Intelligent Money?
Because the app handles personal financial information, security should be considered before connecting accounts. Quicken provides security measures intended to protect account data and uses authentication options where available, but no online service can guarantee absolute protection. Use a strong, unique password, enable device security or biometric login when offered, keep the app updated, and avoid accessing financial dashboards on unsecured public networks.
Is Quicken: Intelligent Money suitable for beginners and everyday budgeting?
The app can be suitable for beginners who want to see spending patterns, organize transactions, and create a more structured budget. However, users who connect several accounts may need some time to categorize transactions, correct duplicates, or adjust budget settings. The experience is generally more valuable when the information is reviewed regularly. It is a budgeting and organization tool, not a replacement for professional financial advice.











